Life Rate for Move-Up Buyers
Move-Up Buyer Strategy
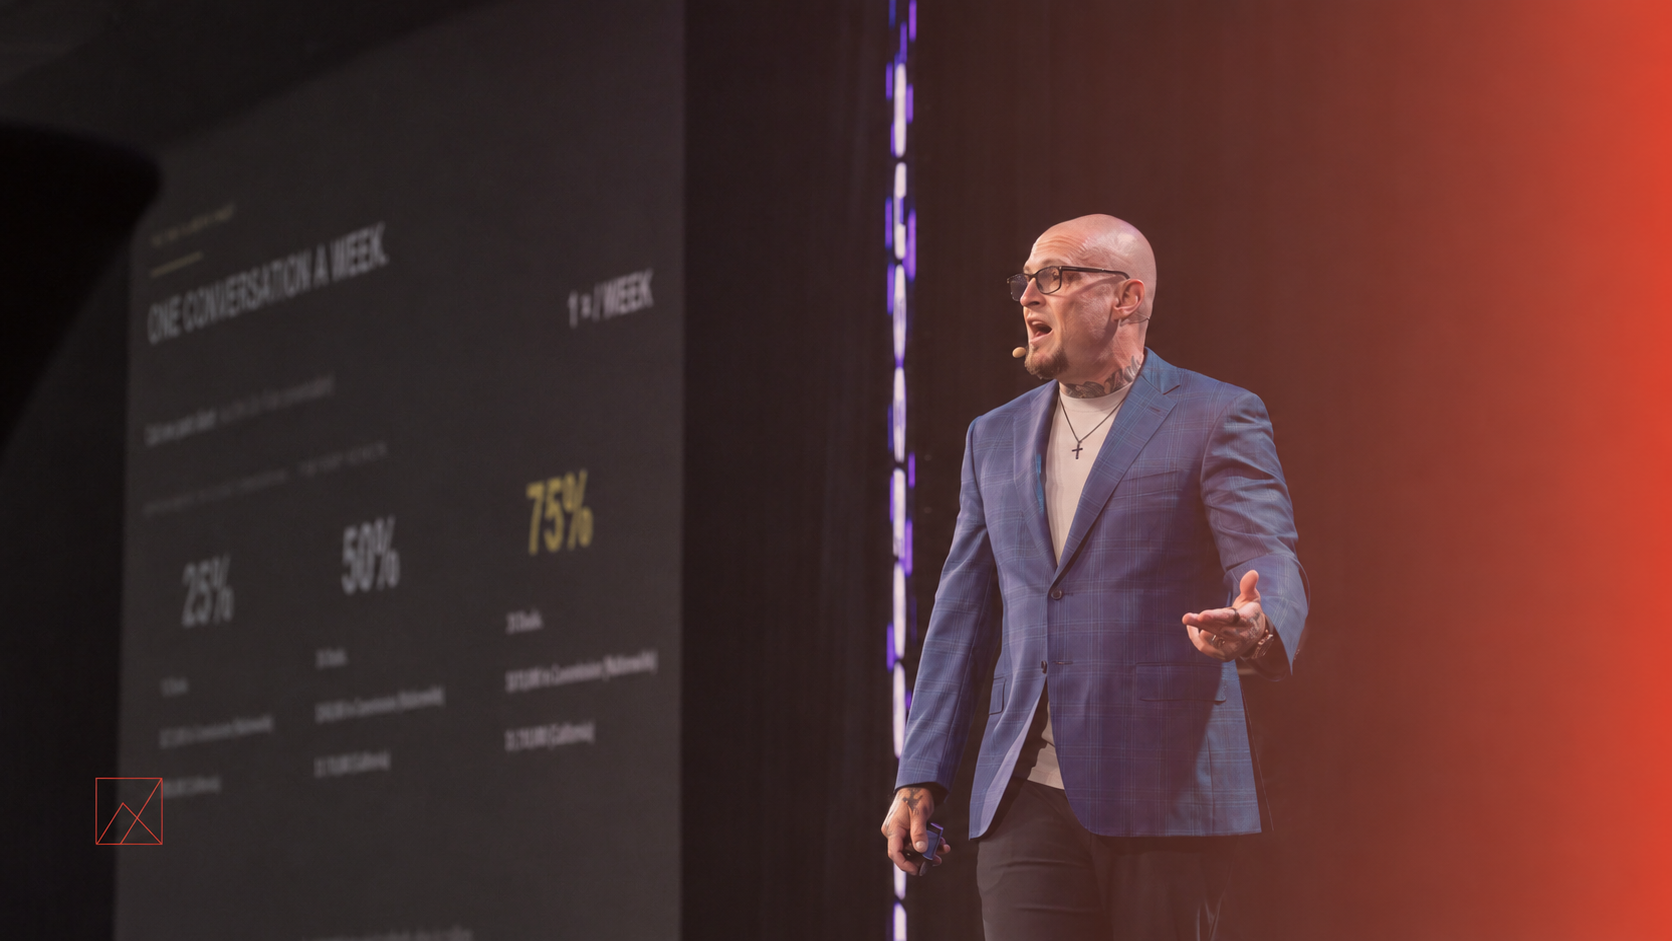
At the 2026 Tom Ferry Success Summit, JJ Mazzo challenged the idea that homeowners with low mortgage rates are automatically locked into their current homes.
His “Life Rate” concept widens the conversation beyond the mortgage rate and looks at the client’s complete monthly financial picture, including other debt, available home equity, the reason for the move, and a professionally modeled next-home scenario.
The framework’s core message was that the move-up market has not disappeared. Some homeowners still want a different home. They may simply need a clearer way to understand the math and the options.
A low mortgage rate is only one part of the picture
A homeowner may have a very attractive mortgage rate and still be carrying much more expensive debt elsewhere.
The framework specifically discussed credit cards, auto loans, HELOCs, and other recurring obligations.
His point was not that a homeowner must move or use equity in one specific way.
It was that comparing only the old mortgage rate with a new mortgage rate can hide the rest of the household financial picture.
For a real estate professional, this creates a better starting question:
What is the client’s total monthly outlay, and what housing problem are they actually trying to solve?
Any lending, debt, tax, or financial recommendation belongs with the appropriately licensed professional. The agent’s role is to help organize the housing side of the conversation and bring the right experts into it.
The hidden market is the homeowner who still wants to move
The framework describes a group of homeowners who appear “locked in” but still have real reasons to change homes.
More space.
A different location.
A growing family.
A new life stage.
A need for a home that works differently.
The opportunity is not to talk someone out of a good mortgage.
The opportunity is to help them determine whether the low rate is actually the deciding factor once the whole situation is visible.
The framework’s five simple moves
The framework organized the Life Rate conversation into five practical steps.
1. Inventory the debt
Identify the relevant monthly obligations so the client and lender can see the full picture.
That can include the mortgage, credit cards, auto loans, HELOCs, and other recurring debt payments.
2. Determine available equity
Use a realistic market analysis to estimate the homeowner’s equity position.
Equity can affect what options are possible, but the best use of that equity is a financial decision that needs qualified advice.
3. Model the financial scenario
The framework emphasizes running the numbers with a lender rather than relying on assumptions.
This is where potential uses of equity, financing structure, and total monthly outlay can be modeled accurately.
4. Identify the next home
The new scenario needs to solve the client’s actual housing need.
A financial comparison without a meaningful next-home goal is only math.
5. Compare the complete monthly outlay
Now compare the full current situation with the professionally modeled next-home scenario.
The client can see the tradeoffs more clearly than they could from the mortgage rate alone.
The framework framed the agent as more than an information provider
He used the language of becoming a “wealth advisor.”
For a real estate professional, the useful part of that framing is the shift from simply opening doors or quoting a rate objection back to the client.
The agent can help the homeowner understand property value, equity, housing options, and the real estate implications of waiting or moving.
The financial calculations and recommendations still belong with the licensed professionals responsible for them.
That collaboration makes the conversation stronger because the client gets both housing context and qualified financial analysis.
Use math to challenge assumptions, not to pressure the client
One of The framework’s themes was replacing limiting beliefs with a clearer calculation.
A homeowner may assume:
“I can never move because my current mortgage rate is too low.”
The Life Rate conversation tests that assumption against the complete set of facts.
The result may confirm that staying put makes sense.
It may also reveal a workable path to a home that better fits the client’s next chapter.
Either outcome is useful because the decision is based on more than one number.
Real estate leverage was part of the conversation too
The framework also connected homeownership with long-term wealth creation and the leverage built into owning a larger asset with a smaller initial cash investment.
That concept can be educational, but future appreciation is never guaranteed.
Use current and historical market information carefully, label assumptions, and avoid presenting projected returns as certain outcomes.
The strongest use of the idea is to help a client evaluate the long-term role of real estate alongside the immediate monthly-payment conversation.
Make one life rate conversation a weekly kpi
The framework did not present the Life Rate as a rare objection-handling script.
He framed it as a repeatable business-development activity.
One homeowner conversation per week can become a measurable standard.
Track:
- Life Rate conversations offered.
- Conversations completed.
- Lender scenarios requested.
- Housing needs identified.
- Next actions scheduled.
That gives the business a way to turn the framework into consistent outreach instead of waiting for a homeowner to raise the objection first.
FAQ
What is the framework’s life rate?
It is a way to look beyond one mortgage rate and consider the homeowner’s broader monthly debt obligations, equity position, housing need, and lender-supported next-home scenario.
Does the life rate mean a homeowner needs to use equity to pay off debt?
No. the framework discussed equity as a potential source of options, but any decision about debt, financing, taxes, or use of equity belongs with appropriately licensed professionals.
Why does the framework call this a hidden market?
Some move-up buyers still want a different home but assume their current mortgage rate makes moving impossible. A complete scenario can reveal whether that assumption is accurate for their situation.
How can an agent use the life rate in the database?
Select appropriate past clients or homeowners for a periodic housing-options conversation, involve a qualified lender when modeling is needed, and track the next action rather than treating the conversation as a one-time pitch.
Bottom Line
The message was not that every homeowner with a low mortgage rate needs to move.
It was that the mortgage rate alone does not tell the whole story.
Start with the life reason. Look at the complete monthly picture. Understand the equity position. Bring in a qualified lender or financial professional to model the options. Then let the client compare the real tradeoffs.
That turns “I can’t move because of my rate” from an assumption into a decision supported by better information.
Put it into action
Choose one past client or homeowner who has mentioned wanting a different home but feels locked in by their rate. Prepare the real estate information you can responsibly provide, identify the housing need, and coordinate a lender-supported Life Rate conversation so the client can compare the complete scenario.
For the complete Success Summit 2026 recap, explore Janet’s 20 Real Estate Lessons From Tom Ferry Success Summit 2026.
Would you like to talk through how this applies to your business? Email Janet at hello@janetmiller.coach or send her a DM on Instagram at @janetmiller.coach and tell her what you are working through.